The American grandma who convinced China to buy houses on credit never existed
For nearly three0 years, a simple parable about two elderly women in heaven shaped the financial lives of hundreds of millions of Chinese people. It has now been confirmed as a complete fiction—engineered as a policy tool during the late 1990s to persuade a risk-averse public to embrace mortgage loans.
The widely repeated tale contrasted a Chinese grandmother who spent her entire life saving up to buy a home with cash against an American grandmother who took out a bank mortgage in her youth, lived in her house for decades, and paid off the loan just before she died. The narrative was designed to promote the concept of “spending future money” and to dismantle traditional Chinese ideas about avoiding debt.
The massive spread of this fable coincided with China’s landmark urban housing reform in 1998. That year, the State Council issued a directive that effectively ended decades of the traditional “welfare housing allocation” system and initiated the country’s transition toward a market-driven property sector. In the early days of these reforms, however, banks remained cautious about issuing individual mortgages, while ordinary citizens deeply clung to a traditional savings mindset that viewed debt with extreme suspicion.
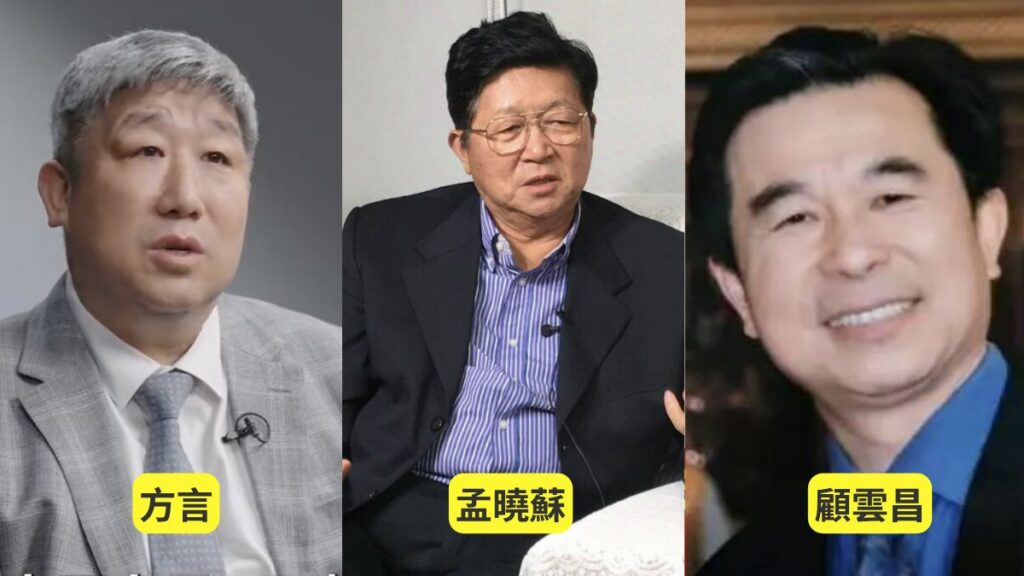
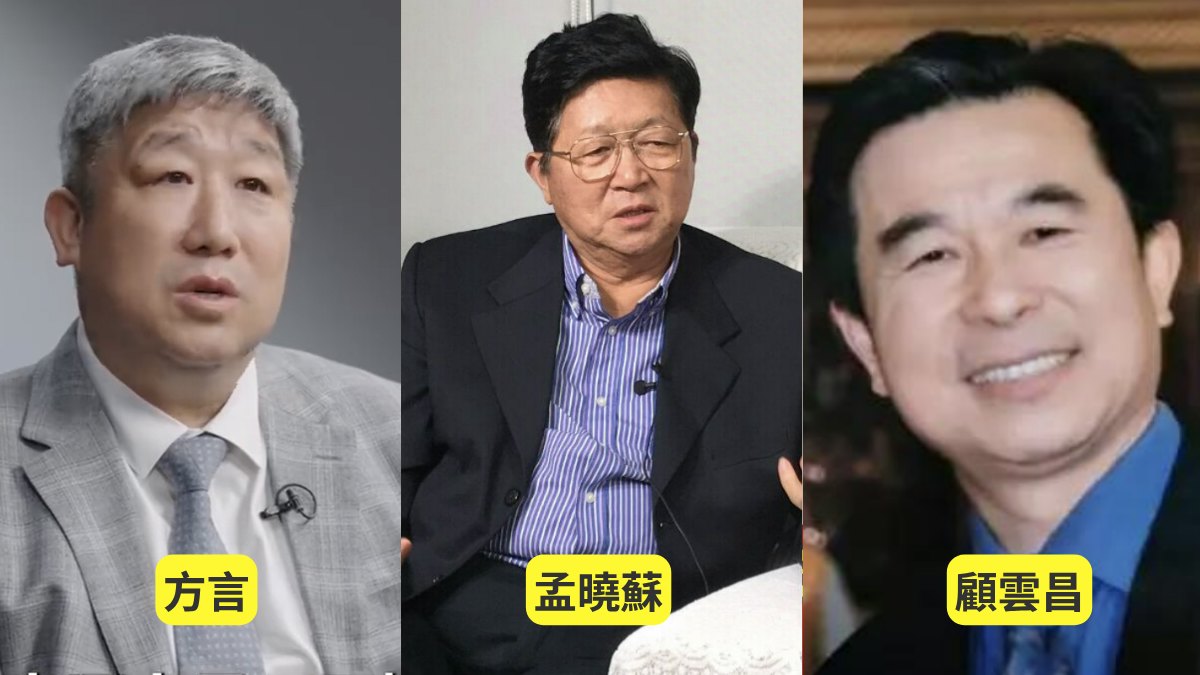
To break through these psychological barriers, government and industry figures worked together to shift public perception. Meng Xiaosu, former chairman of China Real Estate Development Group, previously revealed to state media that Gu Yunchang, former director of the policy research center under the Ministry of Construction, helped popularize modern financial concepts by turning them into accessible stories. The narrative was meant to convey a clear message: rather than saving until old age to buy a home, it was better to use a bank mortgage early and enjoy private property ownership for a lifetime.
The origin of the story was not entirely singular. As early as November 1997, Wang Shi, founder of property giant Vanke, shared an identical conversational example when reporting to a visiting State Council leader in Shenzhen, hinting that the anecdote may have already circulated informally within the industry. Policy researchers later refined and packaged the concept, pushing it nationwide through official communication channels.
Armed with a striking contrast in consumer lifestyles, the story quickly moved beyond real estate training seminars and into mainstream media. It was eventually incorporated into secondary school ideological and political education reference materials by the People’s Education Press, serving for years as a classic textbook example for explaining consumer credit.
As property market cycles shifted, the fable was gradually deconstructed by the very core figures who helped build the housing reform era. In July 2017 and May 2019, Meng repeatedly acknowledged in public forums and media interviews that the story was purely a marketing tactic designed to promote the adoption of mortgages. The late Gu Yunchang also previously admitted to utilizing the parable to guide citizens toward borrowing for home purchases during an anniversary retrospective hosted by China Real Estate News.
While internet interviews have occasionally featured individuals claiming to have personally fabricated the tale, industry checks indicate they were likely part of the execution phase rather than the original masterminds.
Today, the heavy reliance on debt to fast-track homeownership is facing profound reflection amid rising mortgage defaults and a broader property market correction. Looking back at the housing reform journey, a publication affiliated with the People’s Daily previously cited Gu’s late-life reflection: whether in China or the United States, the vast majority of ordinary people ultimately need to work hard for a lifetime to secure a home of their own.