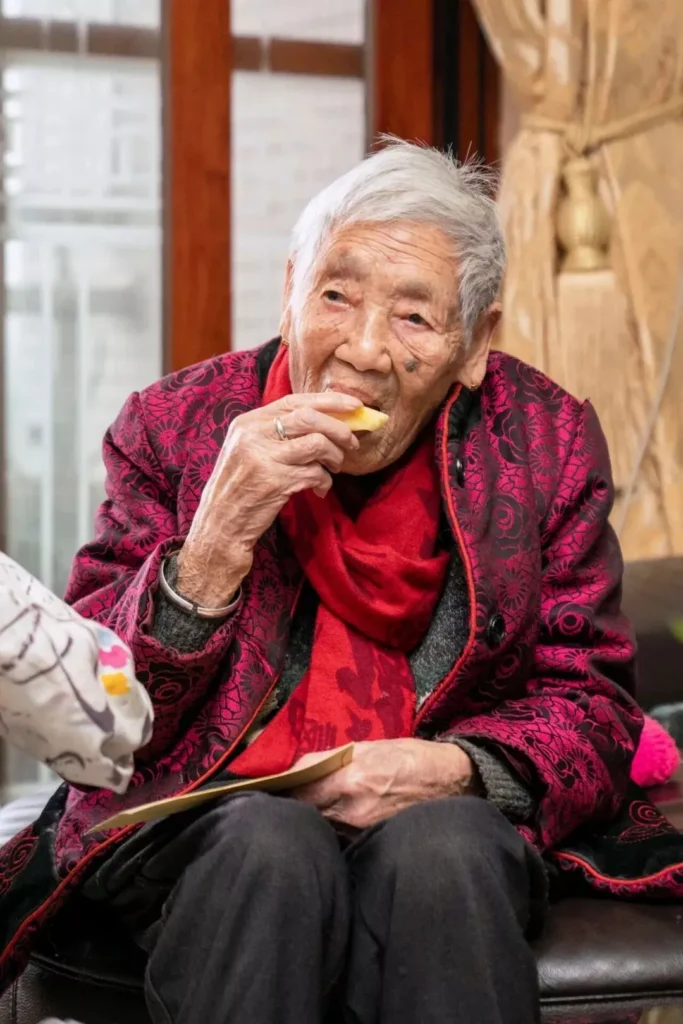
She paid 40,000 yuan in social security at 93. Ten years later, she proved the skeptics wrong
Under the policy guidelines at the time, Lv immediately secured eligibility for pension benefits upon completing the payment, translating to roughly 700 yuan a month.
When her story first hit the headlines, it sparked a fierce public debate. Skeptics argued that for a nonagenarian, trying to recoup a 40,000-yuan investment through a meager monthly pension of under 800 yuan was a mathematical long shot—even a five-year span seemed unlikely to cover the principal.
In the years that followed, whenever retroactive social security contributions became a topic of public discussion, Lv’s case was frequently invoked, though few ever followed up on how her gamble actually turned out.
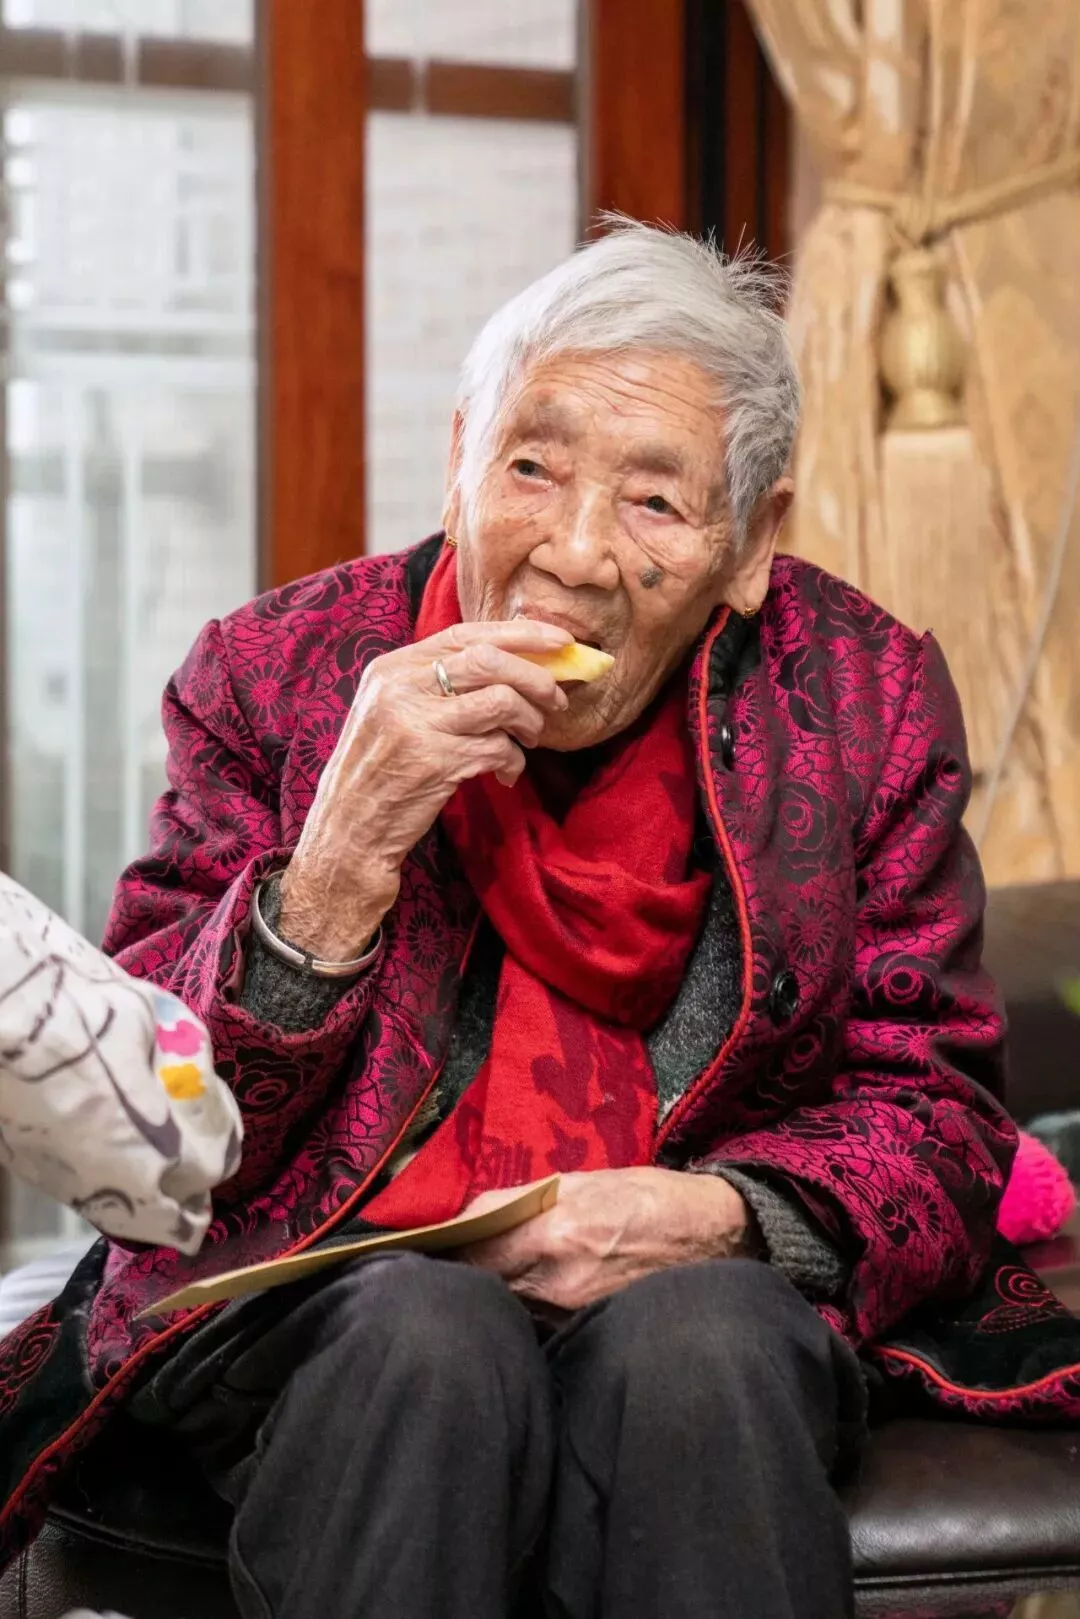
By 2021, a centenarian Lv sat down for an exclusive interview to reflect on her decision a decade prior. "I never expected that at my age, I would still have the chance to pay into social security, and getting over 700 yuan a month is even more than I used to earn back when I was working," she said candidly.
"Now that I have been collecting my pension for nine years, I must take good care of my health and hope to live a few more years." While no definitive reports about Lv have emerged since, her case offers a fascinating numbers game: by 2021, her retroactive contribution had long surpassed the break-even point and more than doubled in return. At roughly 700 yuan a month, her annual payout came to about 9,000 yuan, pushing her nine-year total past 80,000 yuan.
Of course, this back-of-the-envelope calculation leaves out nine years of inflation and interest rates. Yet even factoring those macroeconomic variables in, her financial outcome remained firmly in the black. Such an inspiring financial anecdote naturally prompts contemplation about the future: for those who began paying into the social security system in 2011 and have now completed 15 solid years of contributions, retirement remains a distant horizon.
Should the current pension framework endure by the time today’s thirty-somethings reach retirement age—when retirement thresholds may edge toward 70, requiring upwards of 48 years of continuous contributions alongside steady employer-employee matching ratios—the ultimate payout and break-even timeline remain shrouded in uncertainty. One can only hope to match centenarian Lv’s longevity and live long enough to witness the shifting tides of time.