China’s Singles’ Day turns 18. Merchants are quitting and the magic is gone
Produced by DeepWeb, Tencent News Xiaoman Studio
As another November approaches, the once-frenetic anticipation of asking “When does Singles’ Day start?” has largely faded into the background of China’s retail calendar.
In past years, shoppers would meticulously curate their online shopping carts weeks in advance, bracing for midnight buying sprees. Merchants stockpiled inventory and burned the midnight oil drafting marketing campaigns, all to chase the record-breaking gross merchandise value (GMV) figures trumpeted by major e-commerce platforms.
Today, as China’s iconic shopping festival enters its 18th year, its magnetic pull has fundamentally shifted. Consumers no longer feel compelled to hoard goods at midnight, merchants increasingly view participation as an optional—and often costly—chore, and platforms are hastily rewriting their playbooks, stripping away convoluted discount schemes in a desperate pivot from brutal price wars toward service quality.
The idiosyncratic ritual that once drove millions of Chinese consumers to stay up all night has largely lost its sheen. Its original magic is, for all practical purposes, dying.
The Breakdown of a Decades-Old Growth Model
Many veteran online shoppers still reminisce about the festival’s golden era a decade ago, when 50% discounts and straightforward buy-one-get-one-free promotions were the norm. Now, with overlapping promotional windows like the mid-year “618” festival and constant flash sales blurring the calendar, discounting has become the baseline operating mode rather than a special event.
Cao Lei, director of the China E-Commerce Research Center, notes that the festival’s waning allure is directly tied to the normalization of promotions. When deep discounts are stretched across the entire year—compounded by labyrinthine rules like complex cross-store minimum spending thresholds and dubious pricing practices where items are marked up before being marked down—consumer trust steadily erodes. Impulsive hoarding has given way to pragmatic, need-based purchasing.
For merchants, signing up for the festival is no longer a no-brainer. Wang Hua (a pseudonym), a Taobao merchant who has skipped both the 618 and Singles’ Day events for three consecutive years, describes a brutal catch-22 facing small and medium-sized enterprises (SMEs): “Either you don’t participate and get ignored by the algorithm’s traffic, or you participate and make zero profit.” The sales bump from promotional events often fails to cover platform fees, steep discounts, and promotional costs, while customer service and return logistics expenses eat away at the bottom line. For Wang, survival trumps vanity metrics.
Cao argues that cheap prices alone can no longer anchor consumer attention, forcing the future festival ecosystem to expand from a single-minded obsession with price into a holistic battleground for customer service and user experience.
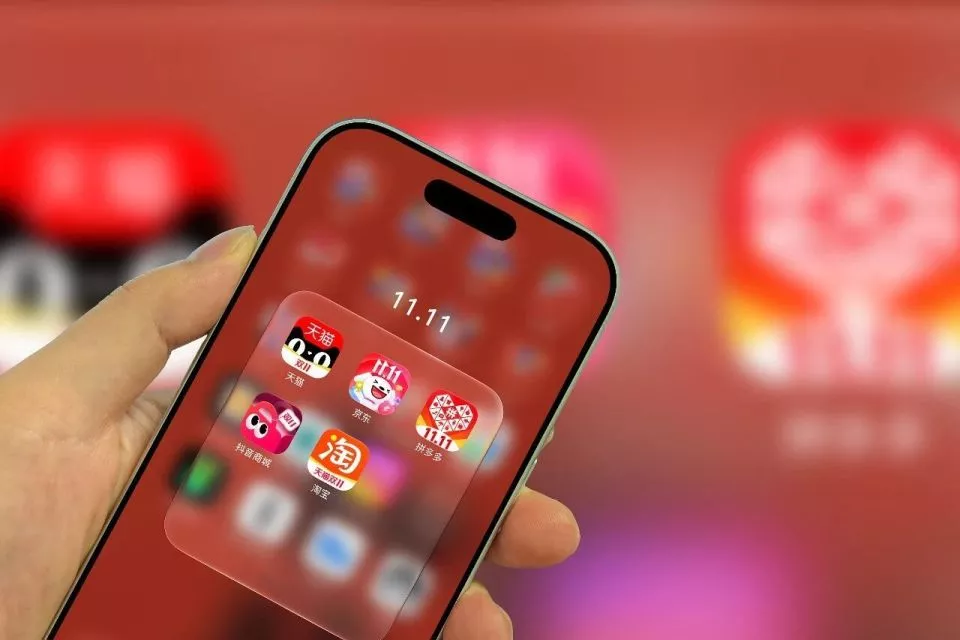
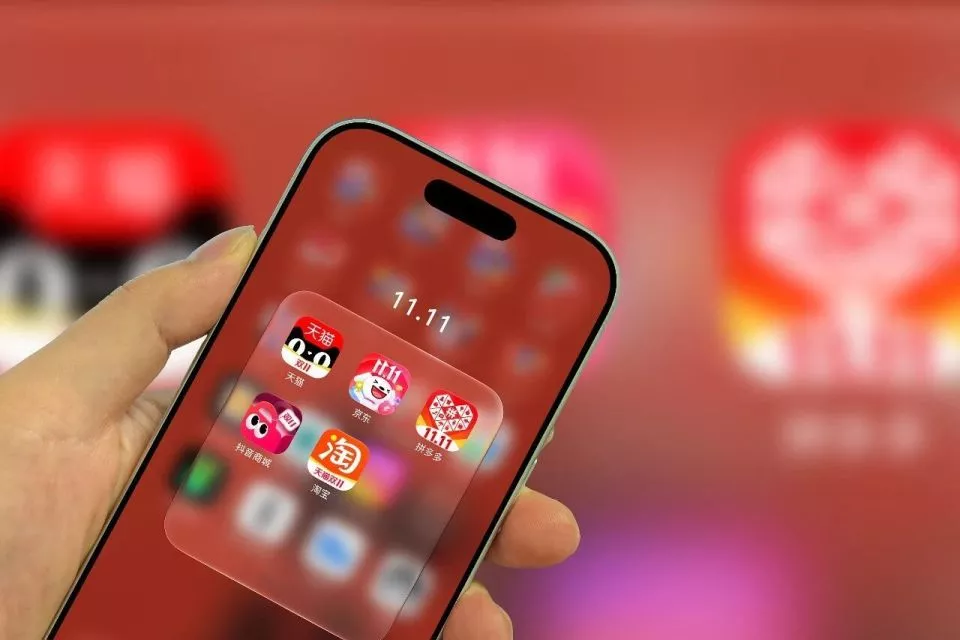
Platforms are scrambling to adjust. As October rolled around, tech giants including Alibaba’s Tmall
, JD.com
, and Douyin E-Commerce unveiled their Singles’ Day blueprints, converging on a shared theme: direct discounts, ready-stock sales, and streamlined mechanics. Tmall scrapped its notorious cross-store spending thresholds in favor of direct merchant discounts paired with platform subsidy vouchers. JD.com ditched pre-sale deposit locking in favor of instant spot-goods transactions, while Douyin leaned into rapid delivery and official subsidies while cutting back on complex cross-store bundling.
At a recent media briefing, Tmall President Jialo explained the rationale behind dropping cross-store discounts, noting that the decision followed extensive consultations with merchants. The overarching goal, he stressed, was to make the rules transparent and simple.
While some merchants welcome the simplification, many SMEs remain deeply disillusioned.
Why Small Merchants Are Turning Their Backs on the Festival
Zhang Feng (a pseudonym), a garment e-commerce operator, points out that registering for Singles’ Day essentially means submitting to mandatory price cuts, while the financial support and traffic tilt provided by platforms are marginal at best. Because promotional discounts now run year-round, the incremental order volume generated on Singles’ Day itself has shriveled.
“Back when the Taobao ecosystem still had explosive organic growth, merchants would prepare months in advance,” Zhang recalls. As the festival’s contribution to his annual revenue shrinks, so does his enthusiasm.
According to Wang Hua, joining the event typically requires surrendering 10% to 15% in profit margins, alongside mandatory promotional outlays. Once platform commissions, ad spending, and return losses are factored in, profitability rarely matches the bump in sales. Furthermore, the traffic dividends generated during the event flow almost exclusively to heavyweight brands and top-tier merchants, leaving SMEs fighting for scraps. With organic traffic drying up, merchants are forced to rely on paid traffic acquisition. “You have to spend money to get orders; platforms simply don’t give away free organic traffic anymore,” Wang said.
He recalls the early days when Singles’ Day lasted a single day, and a modest shop averaging 100 daily orders could suddenly rack up thousands within 24 hours. Today, even a 10% to 20% bump during the festival is considered a win, yet that marginal revenue is immediately swallowed by advertising expenses and price concessions.
Yet opting out carries its own heavy penalty. Merchants who skip the event risk sliding down platform rankings, losing algorithmic visibility, and seeing their baseline traffic throttled. It is a punishing binary: lose traffic if you stay out, lose money if you jump in.
Another merchant, Nan Zhi (a pseudonym), notes that when promotional discounts and platform commissions combine, certain products absorb up to 20% to 25% of the retail price in overhead, squeezing margins to the bone. To survive, many sellers inflate base prices ahead of the festival so they can offer steep-looking discounts while protecting their actual margins—a practice that has repeatedly drawn consumer backlash over deceptive pricing.
For resource-strapped SMEs lacking organic traffic, the consensus is unanimous: raw order volume is no longer a valid yardstick for success. Net profit is the only metric that matters.
The Elusive Promise of AI Integration
Recognizing these systemic frictions, major platforms are pinning their future growth hopes on three new frontiers: enhanced customer service, expanded product variety, and artificial intelligence.
This year, JD.com doubled down on spot-goods discounts while prioritizing service upgrades, rolling out over 100 granular service sub-categories. The company also embedded cutting-edge tech—including AI shopping assistants, virtual livestreamers, and autonomous delivery robots—across its retail and logistics operations.
Tmall focused on brand expansion and new product launches, aggregating 1 million global brands and over 70 million product SKUs, both setting historic highs. In the month leading up to the festival, the number of merchants launching maiden products on Taobao and Tmall surged 64% year-on-year. In a novel move, Tmall even listed AI tokens as a distinct retail category for the first time, allowing domestic large-model developers like Zhipu and MiniMax to sell token subscription packages directly through their Tmall flagship stores.
However, interviews with multiple e-commerce operators reveal that platform-provided AI tools are still falling short of practical expectations. AI-generated marketing imagery often suffers from visual distortion and requires heavy manual retouching before it can be deployed. Compounding the frustration, many advanced features carry paywalls, damping merchant enthusiasm. Whether AI can genuinely lower operating costs or meaningfully lift conversion rates remains unproven by hard data.
As Singles’ Day marks its 18th year against a backdrop of fading novelty and commercial fatigue, survival will belong not to the platforms shouting the loudest discounts, but to those capable of delivering sustainable, tangible value to both consumers and merchants alike.